£3,000 Trading Allowance: What It Means for Your Side Hustle
November 4, 2026
Can HMRC Track Vinted Sales? What UK Sellers Need to Know
November 19, 2026
Marketplace VAT for UK sellers is due to change from 1 October 2027. From that date, online marketplaces become responsible for collecting the VAT on sales by UK businesses that are VAT-registered, or that sell more than £90,000 a year on a single platform. The change was announced at the Autumn Budget on 28 October 2026, with legislation and HMRC guidance to follow.
If you are VAT-registered and sell on Amazon, eBay or Etsy, you charge the VAT on your sales yourself and pay it over on your VAT return. That is about to move to the marketplace. We first wrote about this in June 2026, when it was only a consultation. The Budget has now announced the change, and we have rewritten this article from scratch, alongside our guide to the Autumn Budget 2026 for online sellers.
- What changes on 1 October 2027
- Who is caught: marketplace VAT for UK sellers
- Three sellers, three outcomes
- What it means for your cash flow and bookkeeping
- What is still not decided
- What to do now
- Marketplace VAT FAQs
What changes on 1 October 2027
At the Autumn Budget on 28 October 2026, the government announced that from 1 October 2027, online marketplaces will be responsible for collecting the VAT on sales by UK businesses that are VAT-registered, or that sell more than £90,000 a year on an individual marketplace. That date comes from the Budget costings and is still subject to legislation, so treat both the start date and the detail as subject to legislation.
The rules apply where the goods are in the UK at the point of sale and are sold to a consumer. The VAT due on those sales does not change. Only who collects it changes: instead of you charging VAT and paying it over on your return, the marketplace collects it.
If this sounds familiar, it is. Since January 2021, marketplaces have already collected the VAT on goods in the UK sold by overseas businesses, and on imports of £135 or less. This change simply extends the same idea to UK businesses. The government’s aim is to tackle VAT evasion, so that compliant sellers are not undercut by those who quietly skip the VAT. It expects around 100,000 businesses to be significantly affected, raising £165 million in 2027 to 2028 and £320 million in 2028 to 2029. HMRC’s factsheet sets out the announcement, and the government’s policy paper has the figures.
| Who sells the goods | Who collects the VAT now | From 1 October 2027 |
|---|---|---|
| Overseas business, goods in the UK | The marketplace (since 2021) | The marketplace |
| UK business, VAT-registered | You | The marketplace |
| UK business, not registered, over £90,000 on one platform | You (you must already be registered) | The marketplace (you must still register) |
| UK business, not registered, under £90,000 on every platform and in total | No VAT | No VAT |
| Personal sales, second-hand goods, sales to businesses | Unchanged | Unchanged |
Who is caught: marketplace VAT for UK sellers
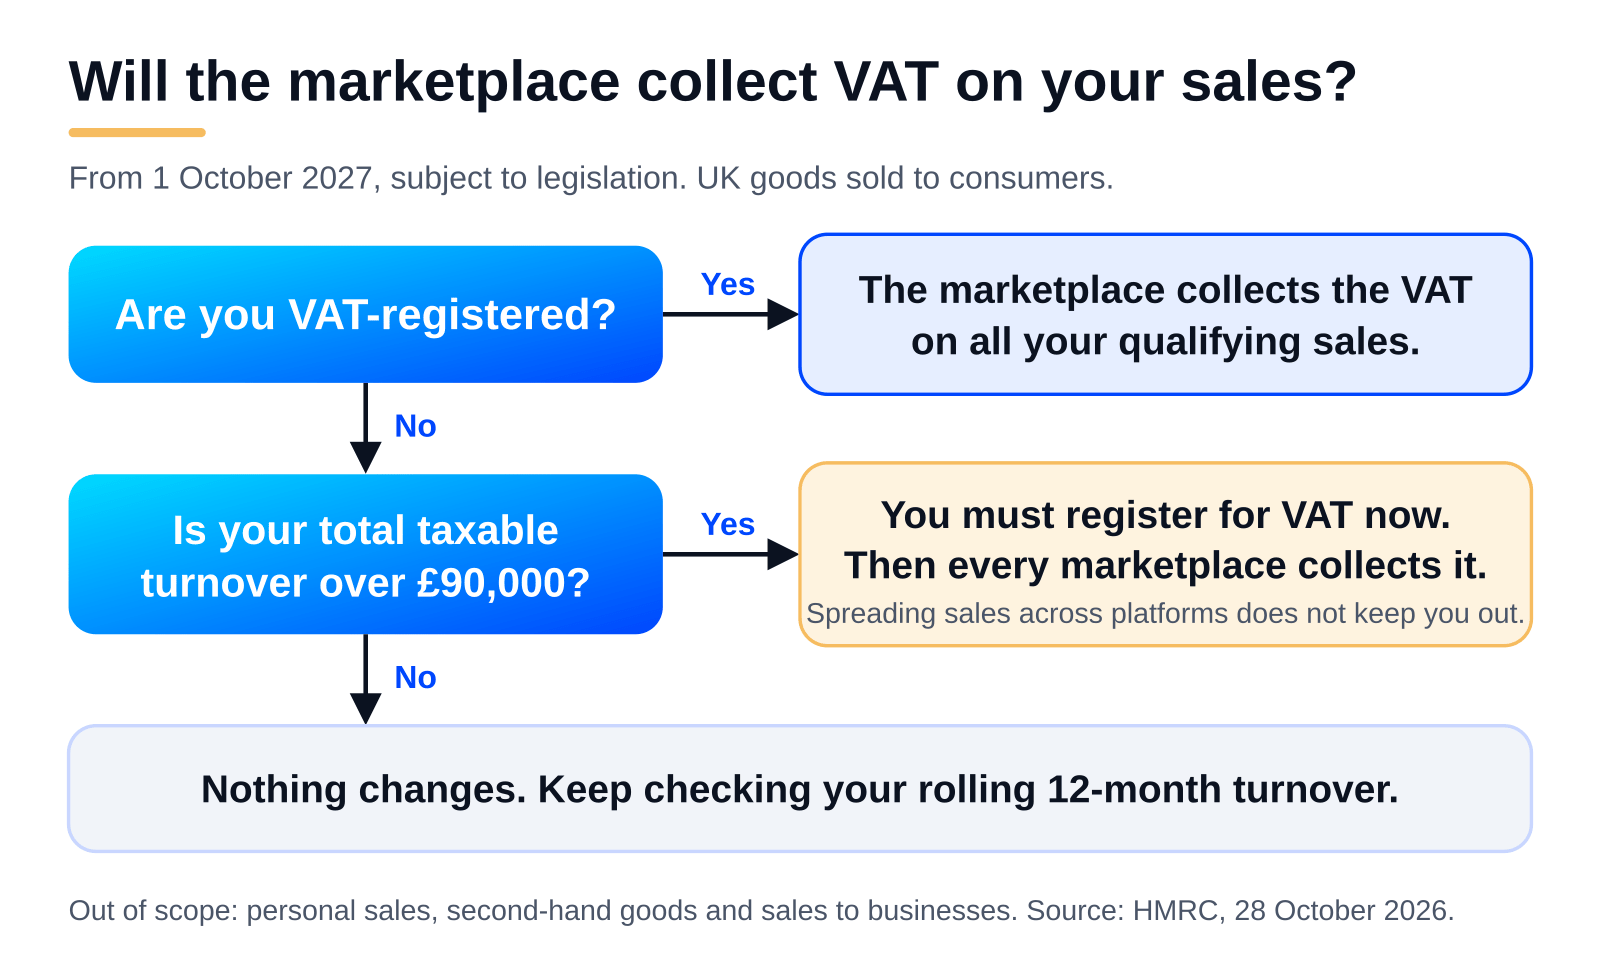
Two groups are in scope. First, if you are VAT-registered, the rules apply to all your qualifying marketplace sales, whatever their value. Second, if you are not VAT-registered but your annual sales on a single marketplace go over £90,000, that platform will collect the VAT on your qualifying sales from 1 October 2027.
Plenty of sales sit outside the rules. Personal sales, people selling their own belongings, are out of scope. Business sellers of second-hand goods keep charging VAT in the usual way. The detailed second-hand rules are still to be set in secondary legislation. And sales to other businesses are out too, so wholesale orders through a marketplace are not affected.
The £90,000 threshold is per platform, not per business
The £90,000 figure, called the Minimum Platform Threshold, applies separately to your annual sales on each platform. The threshold is really a net for sellers who are over the VAT limit but have never registered: if you are selling more than £90,000 on one platform, you are already over the VAT registration threshold and should be registered.
It never overrides the registration rule. The VAT registration rules stay exactly as they are. You must still register for VAT if your total taxable turnover across all channels added together for the last 12 months goes over £90,000, or you expect it to go over £90,000 in the next 30 days. Read our guide to the VAT threshold for UK ecommerce sellers, and see how to register for VAT on gov.uk.
One more thing worth knowing: there will be no special VAT rate relief for small businesses. The consultation floated that idea, and the £90,000 per-platform threshold replaces it. You cannot stay outside VAT by splitting your sales across platforms.
Three sellers, three outcomes
Priya: VAT-registered, Amazon and Shopify
Priya is VAT-registered and sells £80,000 a year on Amazon and £40,000 a year on her own Shopify website, £120,000 in total. From 1 October 2027, Amazon collects the VAT on her Amazon sales to UK consumers. She still charges and reports VAT on her £40,000 of Shopify sales herself, still files VAT returns and still reclaims VAT on her costs.
Because much of her output VAT is now collected by Amazon, the VAT she reclaims on stock and fees could exceed the VAT she still owes, which could put her into a repayment position. Moving to monthly VAT returns could get that money back sooner.
Tom: not registered, eBay and Etsy
Tom is not VAT-registered. He sells £60,000 a year on eBay and £45,000 a year on Etsy, £105,000 in total. Neither platform is over £90,000 on its own, but his total taxable turnover is over £90,000, so he must already register for VAT today.
Once he is registered, both eBay and Etsy collect the VAT on his qualifying sales from 1 October 2027. The per-platform threshold does not let him stay outside VAT, and no amount of spreading sales across platforms will change that. If he should have registered earlier, he must pay VAT on sales made since the date he should have registered, and he might have to pay a penalty for registering late.
Amira: not registered, Etsy only
Amira is not VAT-registered and sells £50,000 a year on Etsy, and nowhere else. She is under £90,000 in total and under £90,000 on every platform, so nothing changes for her. She should keep checking her rolling 12-month turnover, because a strong year could tip her over.
Not sure which side of the line you are on? Our FCCA-chartered team handles marketplace VAT for UK ecommerce sellers every day. Book a free 30-minute call and we will check your VAT position across every platform you sell on.
What it means for your cash flow and bookkeeping
Today, a VAT-registered seller collects the VAT at the point of sale and holds it until the VAT return is due. That quiet gap works in your favour: the VAT sits in your bank account as a working capital cushion, often for several months. Once the marketplace collects it, that cushion goes, because you no longer collect that VAT yourself.
The government’s own impact note says some sellers may need “alternative cash flow solutions”, and some may move into a VAT repayment position, exactly like Priya above. If you are in scope, you will be able to apply to move to monthly VAT returns, which brings repayments back to you faster.
On the bookkeeping side, settlement reports and payouts will need mapping carefully, so that VAT the marketplace collected is not recorded as VAT you still owe. If you use a connector such as Link My Books or A2X to feed Amazon or eBay data into Xero or QuickBooks, its tax settings will need reviewing once HMRC publishes its guidance. Our ecommerce accounting team sets these tools up for clients every week.
And remember what stays with you: sales on your own website, for example a Shopify store, are not marketplace sales, so you keep charging and reporting VAT on them yourself as normal.
What is still not decided
Plenty of detail sits in secondary legislation: the level of the threshold, exactly how it works, the treatment of second-hand goods, the start date and more. HMRC will publish detailed guidance before the start, including any accounting changes sellers need to make. As of 11 November 2026 that guidance has not been published.
Two things are still genuinely open. How the change interacts with the Flat Rate Scheme has not been decided; the government said it will take more time to consider it. And the exact VAT accounting treatment on your return is not yet confirmed either, and HMRC’s guidance will explain it. Read the government’s policy paper for the full detail. We will update this article when HMRC publishes its guidance.
What to do now
No panic is needed. The start date is nearly a year away, and there is plenty of time to get your numbers straight. Here is what we would do between now and then.
- Check your rolling 12-month taxable turnover across every channel, including your own website and any cash or market-stall sales.
- Split your sales by platform so you know exactly where each one stands against the £90,000 threshold.
- Separate second-hand, business and personal sales from your new-goods consumer sales, because only the latter are affected.
- Plan for the VAT cushion going. If marketplace VAT moves off your return, talk to us about monthly returns and your cash flow before it lands.
- Make sure your bookkeeping records VAT by sales channel, so marketplace-collected VAT and your own VAT never get muddled.
If you are already over the VAT threshold and not registered, fixing it now is far better than having a platform’s data expose it later. Most sellers who get this wrong are not trying to dodge anything. They never realised the registration rule caught them, and our guide to common marketplace VAT mistakes covers the usual traps.
Marketplace VAT FAQs
When does marketplace VAT for UK sellers start?
From 1 October 2027. The change was announced at the Autumn Budget on 28 October 2026 and the date comes from the Budget costings, but it is still subject to legislation. Secondary legislation will confirm the date and the detail, and HMRC will publish guidance before the start.
Is the £90,000 marketplace threshold per platform?
Yes. The £90,000 Minimum Platform Threshold applies separately to your annual sales on each marketplace, and it only matters if you are not VAT-registered. If you are registered, every marketplace collects the VAT on your qualifying sales whatever the value. The threshold never overrides the registration rule: if your total taxable turnover across all channels goes over £90,000, you must register.
Do I still need to register for VAT if Amazon collects it?
Yes, if your total taxable turnover across all channels added together goes over £90,000 for the last 12 months, or you expect it to in the next 30 days. The change does not alter VAT registration rules. If you are under £90,000 in total and on every platform, nothing changes for you. If you are already registered, the change does not cancel your registration, and you are likely to still file VAT returns for your other sales and your costs.
Does this apply to Vinted or second-hand sales?
Selling your own clothes or belongings on Vinted is a personal sale, so no VAT is collected on it. Business sellers of second-hand goods keep charging VAT in the usual way, so those sales are unchanged. Sales to other businesses are also out of scope. The rules only cover new-goods consumer sales where the goods are in the UK at the point of sale.
Does it affect sales on my own website?
No. The rules cover marketplace sales only, so sales through your own website, for example a Shopify store, are not marketplace sales. You keep charging and reporting VAT on them yourself, on your normal VAT return, exactly as you do today.
Talk to a UK ecommerce accountant
If you’d like a hand applying any of this to your business, our FCCA-chartered team works with over 700 UK ecommerce sellers across Amazon, Shopify, eBay and TikTok Shop. Tell us about your store and we’ll show you exactly what we’d do. Book a free consultation or request a tailored quote.